Tag: energy storage

To solve northern power bottlenecks, future-proof the grid and UK’s energy storage

This article has been republished with permission from The Sunday Times Scotland.
Britain is making meaningful progress in developing a lower-carbon electricity system, thanks in large part to northern low-carbon generation.

The next challenge is building networks and sources of flexibility that can make the most of that investment, while supporting the growth of businesses and communities across the country.

Britain’s energy system is changing rapidly, and as it does it reshapes how regions are positioned to compete for opportunities to grow and prosper.

Offshore wind has become a major source of electricity, solar is growing rapidly, and investment into onshore renewables, energy storage and other forms of generation continues to advance.

Changing how we generate electricity also changes the demands we place on the grid.

One of the most noteworthy challenges is simply where electricity is being generated compared with where it is being used.

Why is electricity generation concentrated in Scotland and northern England?

A majority of the UK’s new generation and storage is being developed in Scotland and the north of England. Together, these areas account for more than half of Britain’s low-carbon generation capacity, while representing less than a fifth of electricity demand.

So, when the wind is blowing strongly in Scotland, for example, there can be a significant electricity surplus produced in the north while demand is much higher elsewhere.

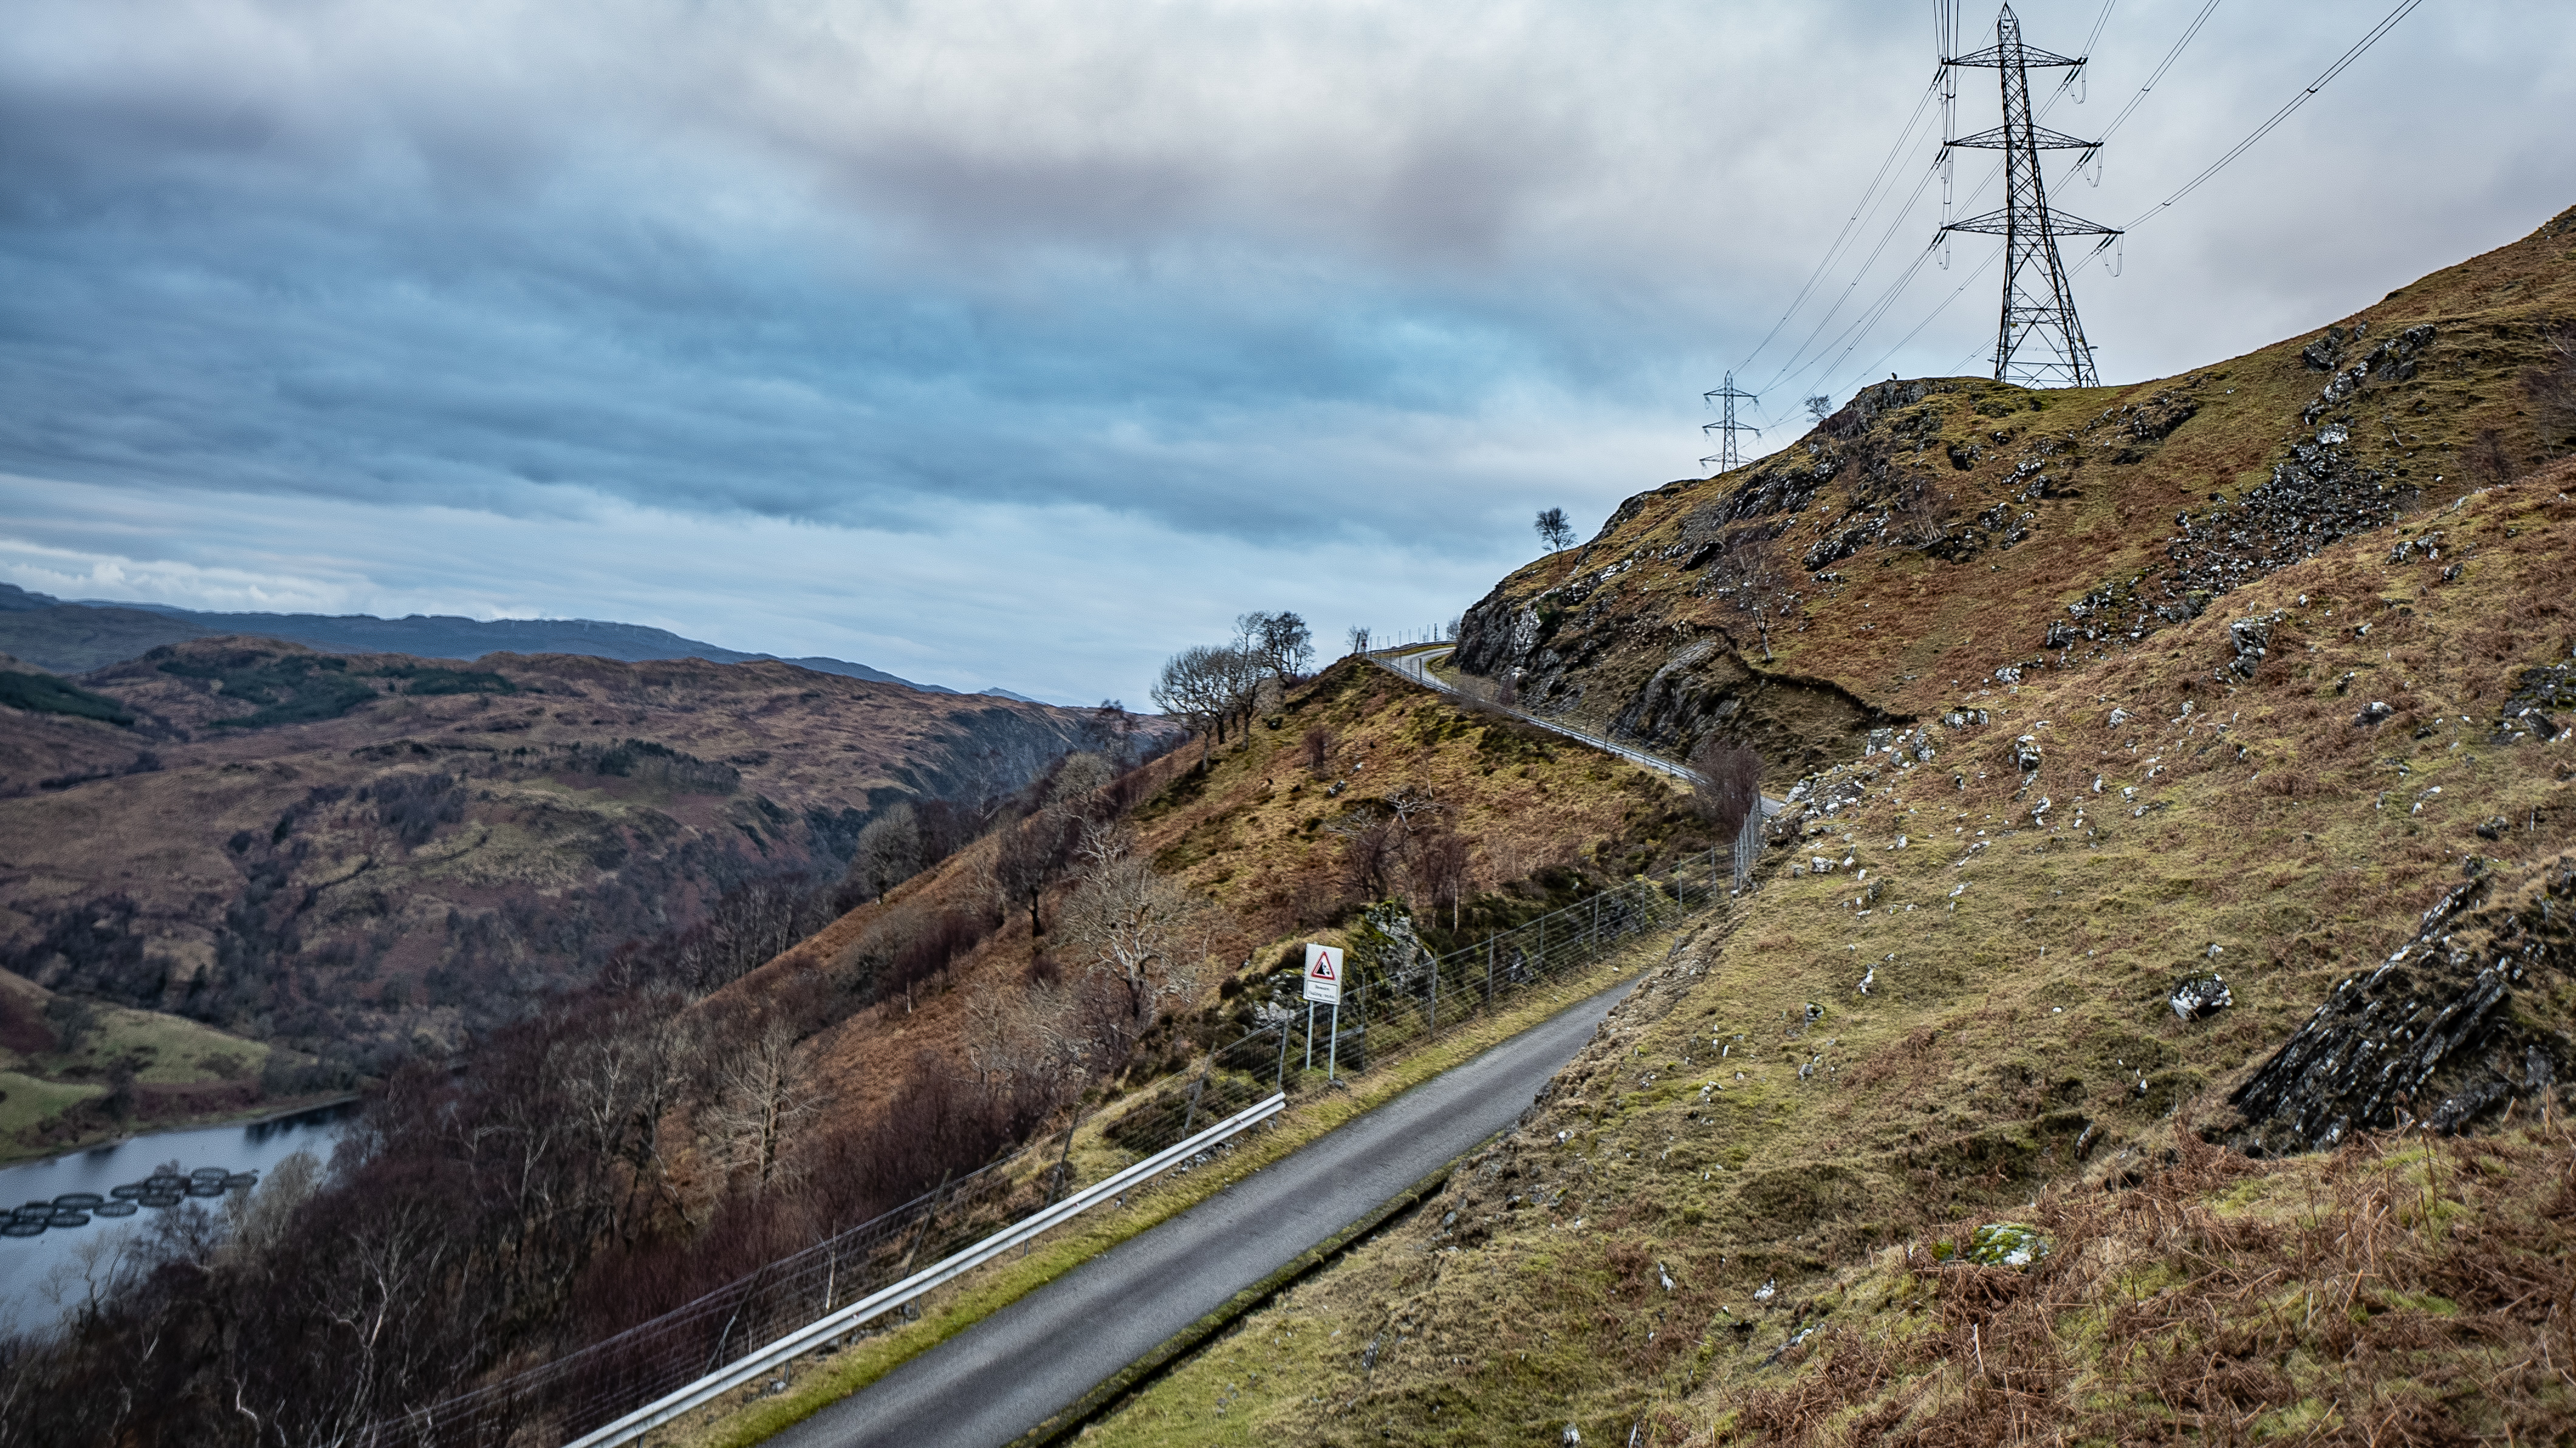
Transmission lines whisk most of this power away to other regions experiencing higher demand, but there are limits to how much the system can handle at one time. Once those limits are exceeded, generators are often compensated to reduce their output – and the UK has already paid out more than £1bn in wind curtailment costs this year.

Solar adds another dimension. Large solar farms are now an established part of the generation mix, while thousands of homes and businesses are generating their own electricity from rooftop panels.

On a sunny summer day, solar can make a significant contribution to meeting demand but, naturally, output varies throughout the day and falls away altogether overnight.

Wind and solar are very different technologies, but they have something important in common: their output depends on the weather, and neither is guaranteed to produce electricity at the same time or place as it is needed.

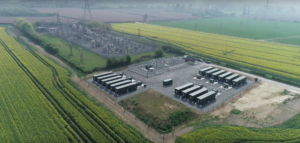
Energy storage from technologies such as batteries and pumped hydro storage can soak up some of this excess power and deploy it when demand is high but, despite a recent battery boom, capacity today is still nowhere near the levels needed to utilise all of it.

Why does Britain need more transmission capacity?

To reduce our reliance on power redirection, there is a clear need to improve the network itself. That means continuing to invest in high-voltage transmission infrastructure, including new lines and subsea connections.

High-voltage direct current links will also have an important role to play in moving large amounts of electricity between regions.

This is particularly relevant as electricity becomes more important to the wider economy.

We need to think about the electricity network not just in terms of keeping the lights on, but as part of the infrastructure that supports economic growth.

A business deciding where to build a new factory, data centre or other major facility needs to know that it will be able to get the electricity it requires. Long connection times can make that decision much harder.

How is clearing grid connections backlog helping viable projects move forward?

The legacy first-come, first-served approach left more than 700GW of projects waiting for grid connections, including projects that are less likely to get built or less strategically vital. Prompting the National Energy System Operator’s (NESO) move towards giving greater priority to projects that are viable and strategically important is a sensible development.

We need to make sure that genuine projects can progress, while avoiding a system where network capacity is effectively reserved for projects that are less likely to go ahead. Getting this right will help unlock investment that is currently waiting on the sidelines.

What role do energy storage and flexible generation play in an efficient system?

A system that is increasingly reliant on wind and solar needs to be able to respond to generation changes and demand mismatches.

To maximise renewable generation at scale, the system needs to adapt seamlessly, shifting power across timelines and geographies to meet demand head on. When a diversified generation and storage portfolio is paired with a flexible grid, the system can absorb volatility to keep reliability, affordability and sustainability all stable under pressure.

Our acquisition of Scotland-based asset optimisation platform Flexitricity earlier this year reflects a key component of this mix, incorporating a tech-enabled solution to help streamline how and when organisations use power in response to the needs of the system. Long-duration storage, including pumped hydro, can also help by storing electricity when it’s abundant and releasing it when it’s needed.

Gas and biomass generation can also provide dispatchable power when the system needs it, helping to provide the reliability that consumers and businesses expect. As the generation mix changes, having a range of technologies that can respond at different times will become increasingly important.

It’s critical to remember that no single technology can solve every problem. The electricity system of the future will need the right combination of generation, transmission, storage and flexibility to meet projected demand consistently.

Powering future economic opportunity with a stronger electricity grid

Power is essential to all economy opportunity, and reliable access to power is a game-changing differentiator at both the regional and national level.

As electrification continues to advance across major industries ranging from technology and transportation to manufacturing and healthcare, it’s increasingly clear that power has become a prerequisite for growth.

At the same time, building and upgrading the grid requires engineers, construction workers, manufacturers and a wide range of specialist businesses. Developing energy infrastructure can support skilled jobs and supply chains across the country.

There is an opportunity here to make sure the benefits of the energy transition are felt beyond the places where electricity demand is highest. Scotland and the north of England have enormous renewable energy potential, and better connections can open opportunities and help attract industries that want access to clean and reliable power.

That could be particularly important as Britain looks to strengthen its industrial base and compete for investment in areas such as manufacturing, technology and other energy intensive industries.

Companies like Drax are already working to build out the right mix of low-carbon generation and storage to meet the needs of the future. The next step is to ensure the infrastructure surrounding that generation is capable of keeping pace.

A stronger transmission network, a more effective approach to grid connections and a good mix of flexible technologies will allow us to make better use of the electricity we are already generating.

It will also give businesses, consumers, investors, and governments greater confidence that the power they need will be available when and where they need it.

The energy transition is changing not just how Britain generates electricity, but where that electricity comes from and how the energy system as a whole needs to operate.

If we build the right system, developing the network alongside our changing generation mix, that flexibility will help to insulate against market shocks, improve affordability, unlock future innovation, and strengthen our collective competitiveness for current and future economic opportunities.
Britain’s solar boom needs energy storage to tackle evening price spikes, new report finds

Britain’s rapid growth in solar power is helping cut emissions from the electricity system, but a lack of storage is leaving the grid increasingly exposed to higher prices and periods of tight supply, according to the latest Drax Electric Insights quarterly report authored by independent academics from Imperial College London.

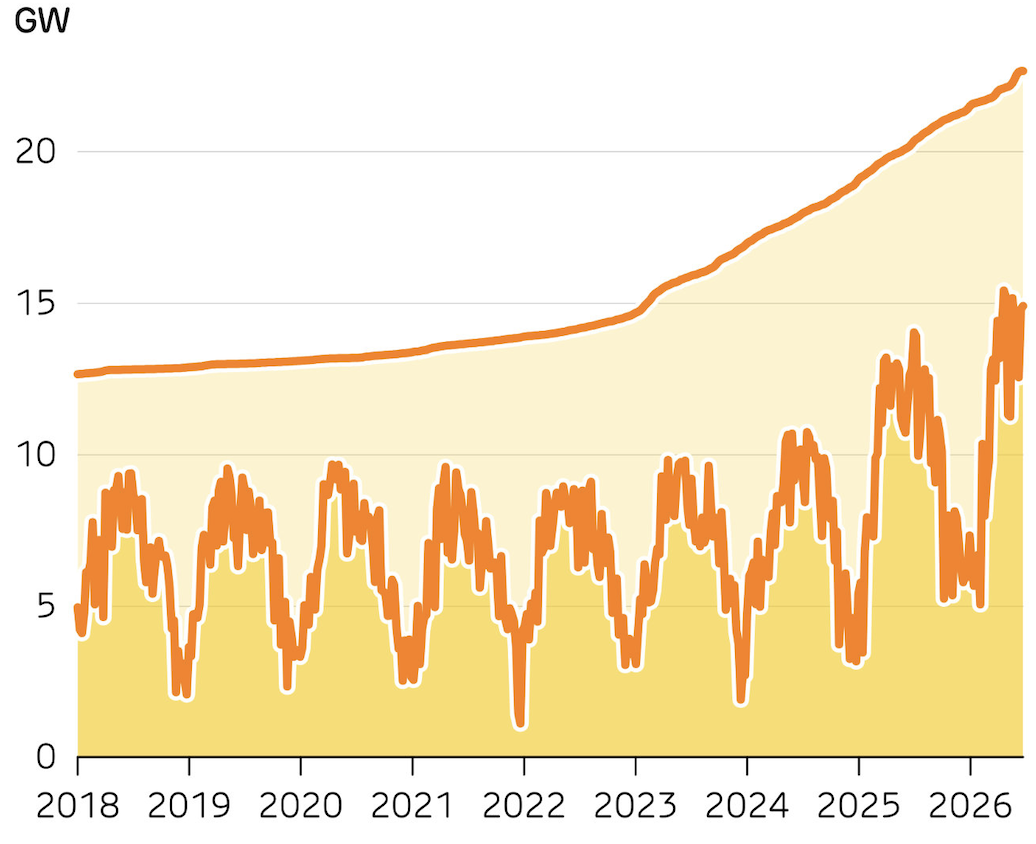
The report found that Britain’s power system can now operate with very high levels of low-carbon generation during periods of strong sunshine. Britain added 2 GW of solar capacity over the past year, and during April, solar generation reached a record 15.4 GW. This helped zero-carbon sources account for a record 98.8% of electricity supply for one half-hour period.

The installed capacity (top line) and peak power output (bottom line) of Britain’s solar panels. 

Strong solar generation reduces Britain’s reliance on gas during the day and helps meet demand for air conditioning during heat waves. The challenge comes later, as solar output falls sharply in the evening, just as electricity demand typically increases, leaving Britain reliant on gas-fired generation to fill the gap. In June, Britain’s wholesale electricity prices after 7pm rose to over double their level at 2pm.

June’s heatwaves exposed the pressures on the system. Wholesale electricity prices rose above £500/MWh, their highest ever recorded in the month of June, while NESO issued its first-ever summertime Electricity Margin Notice.

Heatwaves can put further pressure on the electricity system, as we have seen over the summer. Air conditioning and greater cooling load increases demand just as high temperatures reduce the efficiency of power lines and thermal plants. Calm, low-wind evenings can also add to the pressure, leaving grid operators with fewer sources of generation available to meet the required demand.

Dr Iain Staffell, lead author of the report and Associate Professor at Imperial College London, said:

“Britain’s solar success should not end when the sun goes down. Batteries, pumped hydro and other storage tech can keep that daytime electricity flowing into the evening, which will reduce our reliance on gas and exposure to foreign market price spikes.

“Every new solar panel strengthens the case for storage. We need to build the two together. Otherwise, we risk breaking clean-power records at lunchtime and paying for expensive gas-fired power by dinnertime.”

The Government’s Solar Roadmap aims to put solar panels on an extra 3 million homes, adding a further 10 GW by 2030. The report warns that this will need to be accompanied by investment in electricity storage, flexible infrastructure and other forms of reliable generation if the additional power is to be used effectively.

Will Gardiner, CEO, Drax said:

“There is a feeling that Britain has made real progress in decarbonising its power system and now has a real opportunity to turn some of its energy challenges into solutions that can strengthen energy security, support growth and deliver wider benefits. We need to continue the plan of rolling out homegrown renewables, because they are doing much of the heavy lifting, we are reducing reliance on imported fossil fuels, improving energy security, reducing emissions and lowering bills.

“The key challenge we have is we need to be faster and more joined up. At Drax we’re all about delivering resilient, reliable, renewable power today while investing in the flexible, low-carbon technologies that we need to effectively meet demand. This means looking beyond single technologies, it is a whole-system challenge, where renewable generation, dispatchable low-carbon power, storage and flexibility all need to work together.”

Read the full Electric Insights report here.

ENDS

Media contacts:

Kieran Wilson
E: [email protected]
T: 07729092807

About Drax

Drax’s purpose is to enable a zero carbon, lower cost energy future. Our strategic aims are to be a UK leader in flexible, renewable generation and a global leader in sustainable biomass pellet production.

Our operations

Drax owns and operates a portfolio of flexible, low-carbon and renewable UK power assets – biomass, hydro, pumped storage and OCGT generation – which provide dispatchable power and system support services to the electricity grid.

We are the UK’s largest source of renewable power by output, and Drax Power Station is the UK’s largest single source of renewable electricity by output.

Through our pellet production facilities in North America, Drax is a leading integrated producer of sustainable biomass.

Drax supplies renewable electricity to UK industrial and commercial customers, offering a range of energy-related services including energy optimisation, as well as electric vehicle strategy and management.

Global competition for battery storage

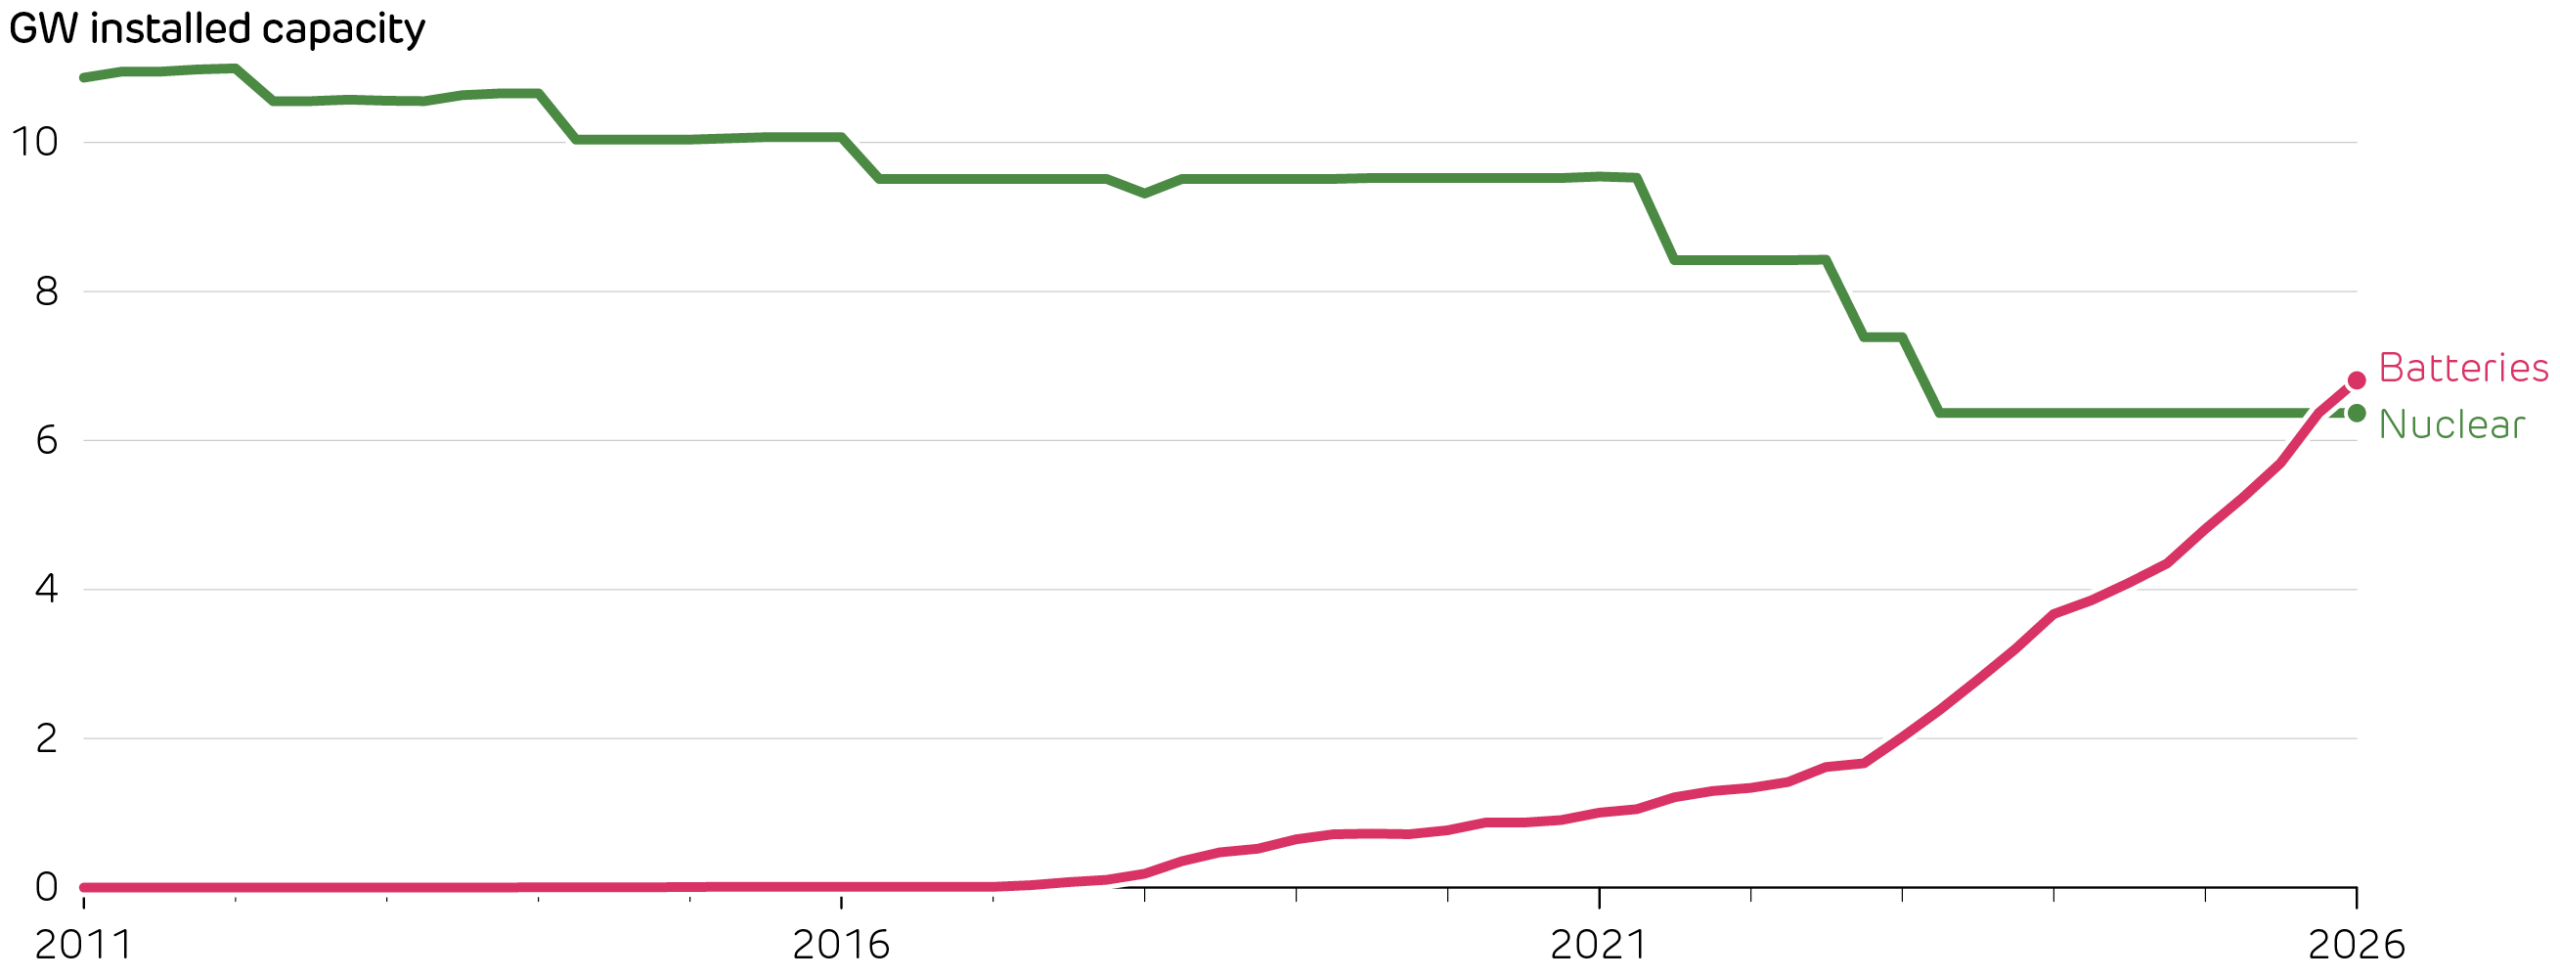
Britain is building batteries faster than any other part of its power system. Installed capacity has tripled in just three years. Batteries can now discharge more power than the entire nuclear fleet, a sign of how quickly the grid is changing. Since construction of Hinkley Point C began, Britain has installed nearly 7 GW of batteries. Hinkley Point’s 3.2 GW of reactors will not come online until at least 2030 (five years late), whereas new battery projects can be built in a matter of months.

Britain’s battery capacity has risen from 10 MW to nearly 7 GW, overtaking the headline capacity of the entire nuclear fleet in under a decade. The two technologies are not directly comparable, as batteries can only discharge for 1–4 hours before recharging, whereas nuclear reactors provide steady output around the clock.

Britain’s battery boom is impressive, but it must compete in a global race for investment. Storage is growing faster overseas as countries seek flexibility to absorb more wind and solar. Investors follow price signals, and battery revenues shift quickly with market regulations and price spreads. Battery revenues vary by one-quarter from year to year, so today’s hottest market can soon become crowded and less attractive.

Turkey shows how quickly the race can shift. It now has Europe’s largest pipeline of battery projects, beating Germany and Italy combined. This surge reflects a fast-growing power system turning to wind and solar to cut imports. Since 2022, new wind and solar projects have had to add battery capacity equal to their generation capacity.

Britain is taking the opposite approach: rather than mandating battery construction, the market decides how much to build. Tighter co-location or balancing requirements could make wind and solar more compatible with system operations, but could risk stalling investment. The Government is leaning towards market signals, with the Clean Flexibility Roadmap aiming to remove barriers and improve price signals for storage.

Energy storage helps Britain use more of the electricity it generates. Batteries respond to short-term swings in supply and demand within seconds, while pumped hydro provides large reservoirs to deliver electricity during longer periods of system stress. Together, they store surplus wind and solar to cut curtailment, and release it when demand peaks to smooth out prices.

To support the Clean Power targets, Britain must more than triple its current storage capacity by 2030. After building 5 GW of batteries in the last five years, Britain now has five years to build the next 20 GW. This will rely on investors remaining convinced this is Europe’s best place to build.

Read the full Q1 2026 Electric Insights report here.

The next PM must move fast to unlock investment in long duration energy storage

For many years energy security was an issue resolved by complex, continent-wide gas pipelines which stretched from Russia into the heart of Europe.

We now know this reliance on Russian gas didn’t strengthen Europe’s energy security – in fact it weakened it.

The UK is less reliant on foreign gas than many countries in Europe in part due to the renewables revolution which has transformed our energy system over the last decade.

The rollout of biomass, wind and solar power has enabled the UK to decarbonise its power grid at a faster rate than any other major economy. And in order to reduce energy bills in the years ahead we need to have more clean, green, renewable power, which is generated in the UK for the UK.

Getting more green energy onto the grid can only be achieved through partnerships between government and private companies. For businesses like Drax, that means having the right policies now, to make large-scale investment decisions for the future, in vital green energy technologies like pumped storage hydro and bioenergy with carbon capture and storage (BECCS).

Drax has submitted planning applications for two major infrastructure projects designed to deliver both of these vital technologies in the 2020s. They form part of a £3bn investment strategy which Drax stands ready to implement this decade, underlining the company’s significant role as a growing, global business at the heart of the green energy transition.

Alongside strengthening the UK’s long-term energy security, these projects will support thousands of jobs and provide a real opportunity for economic growth.

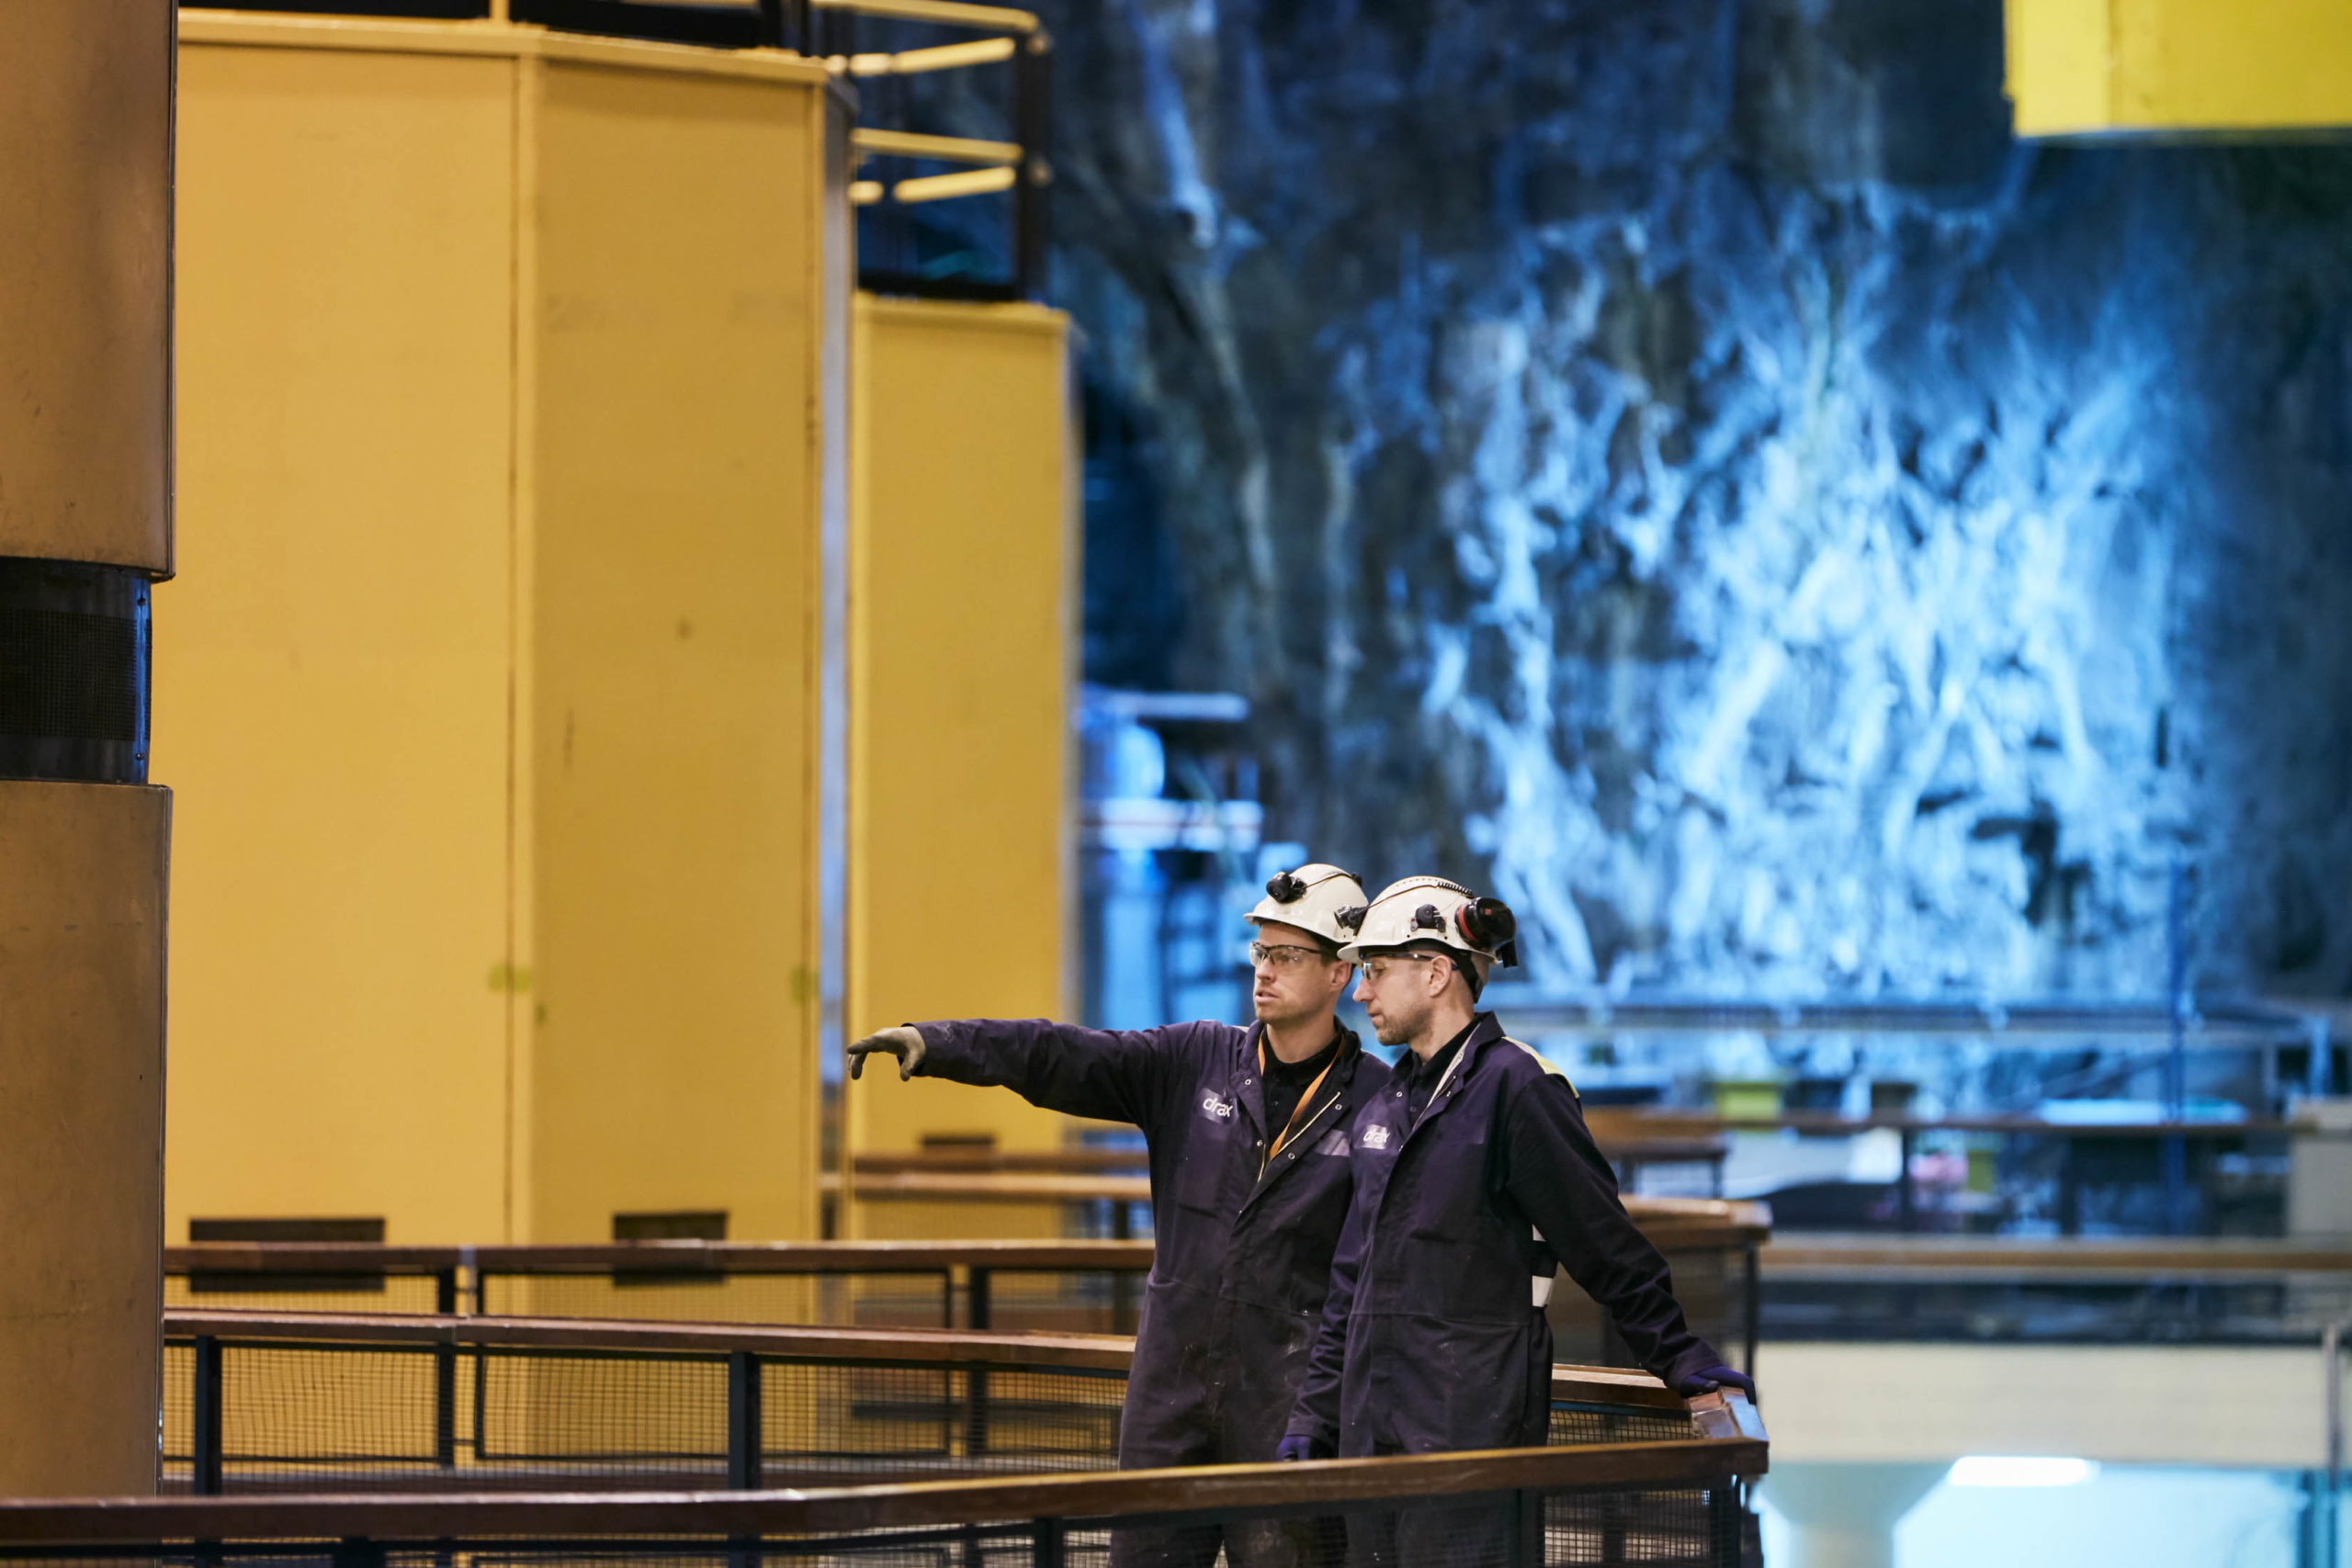
Engineers at Cruachan Power Station

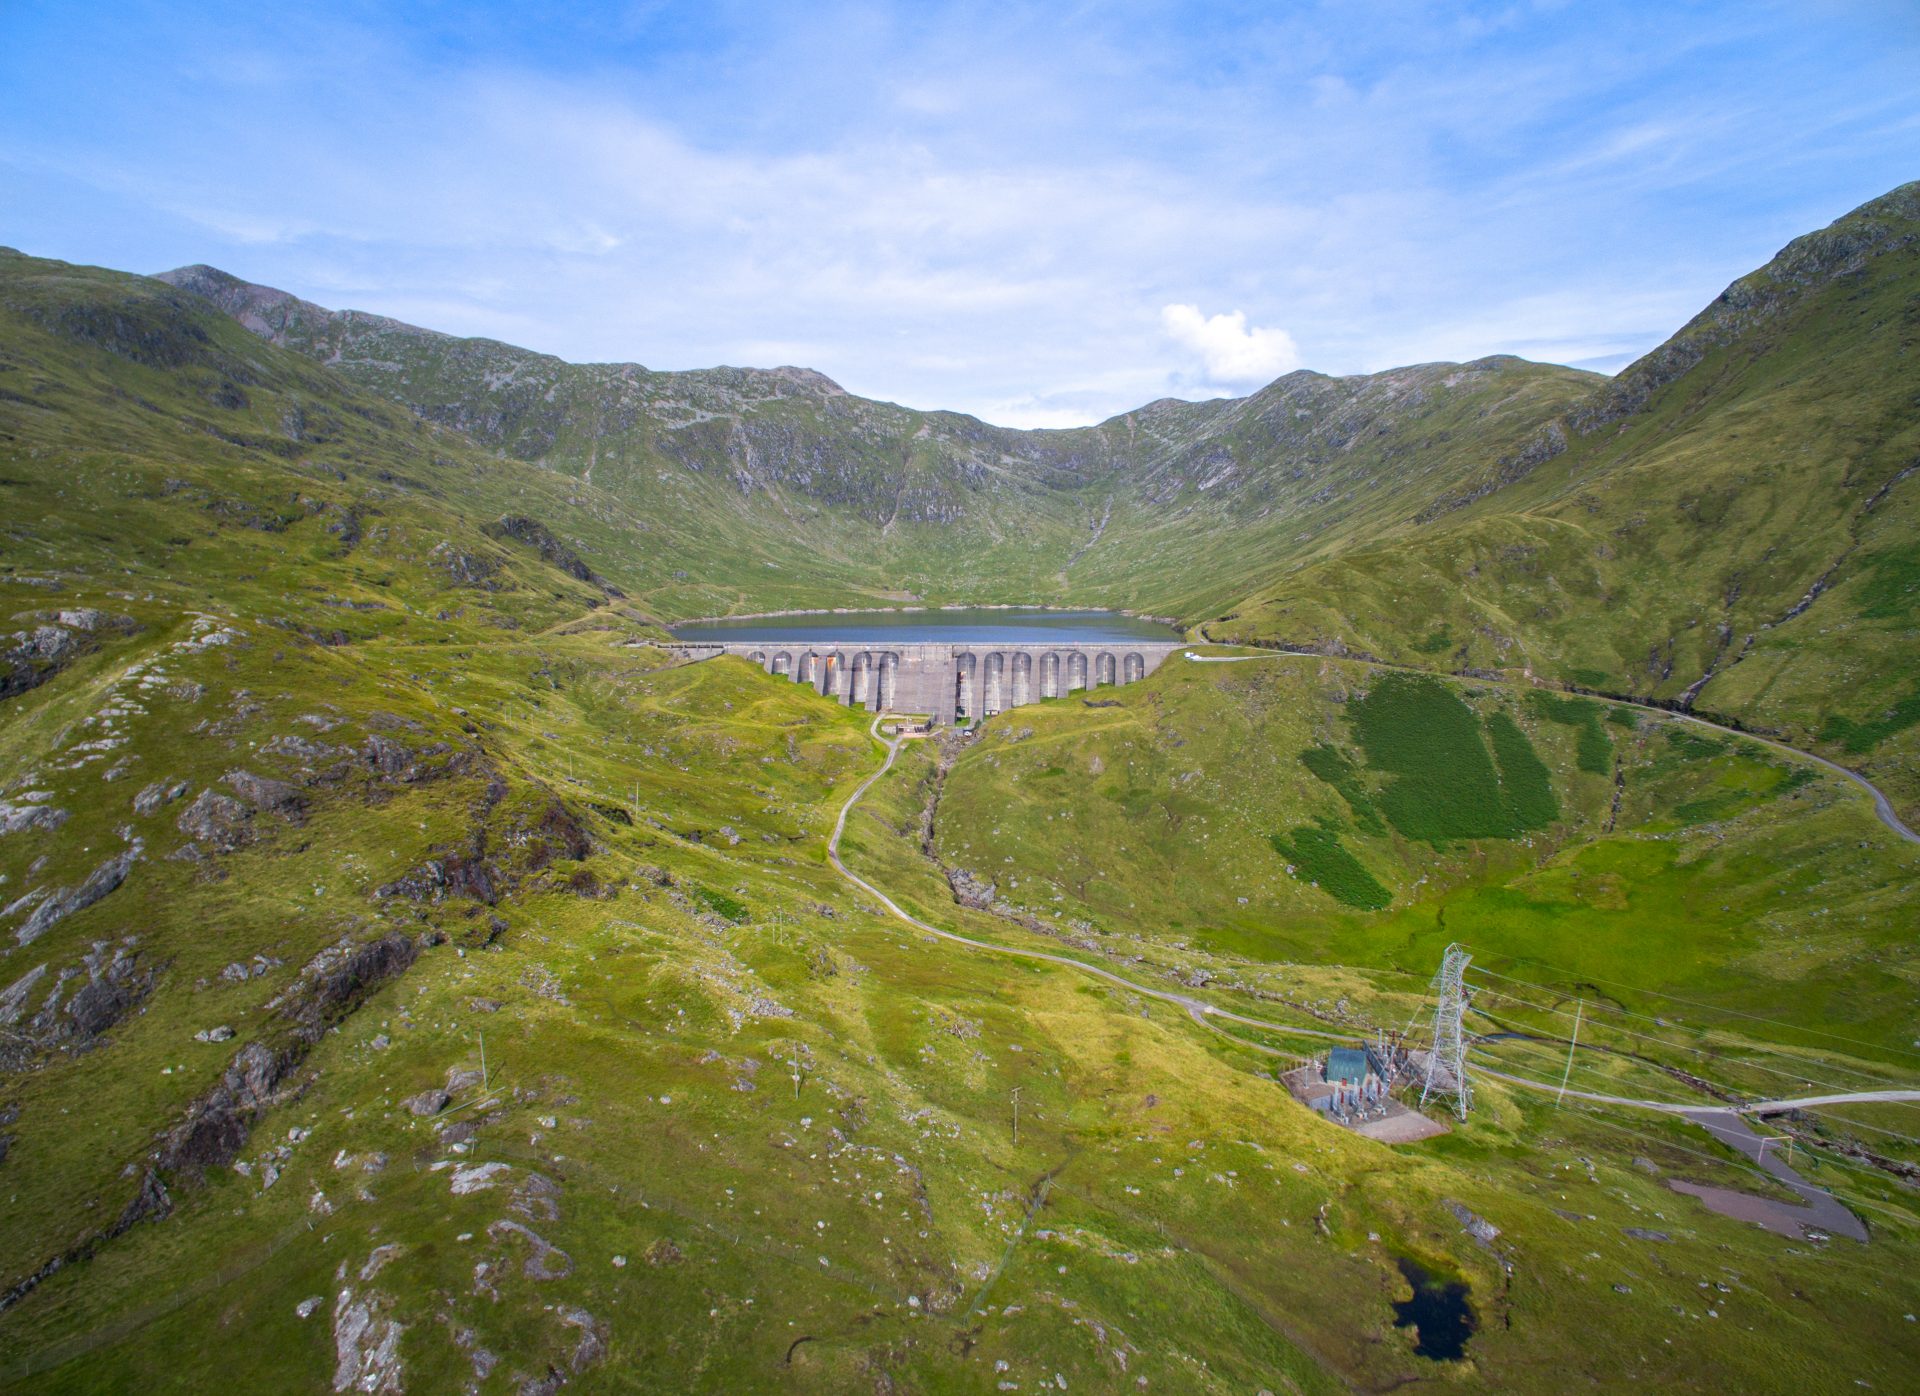
We aim to double the capacity of our Cruachan pumped hydro storage facility in Scotland, supporting energy security and further decarbonisation of the grid, at lower costs.

Over the last two years, due to bottlenecks on the transmission system and a lack of energy storage capacity, enough wind power to supply 800,000 homes each year with renewable electricity, went to waste.

As household bills and global temperatures continue to rise, we can’t afford to let renewable power go to waste like this. We need more storage to harness the wind power available now, as well as the increased capacity being developed the coming years.

The only proven grid scale technology that can store vast quantities of energy for long durations is pumped storage hydro. Sites like Cruachan act like giant water batteries, using excess power from the grid to pump water to an upper reservoir where it is stored, before re-releasing it to generate electricity.

While the UK’s policy and market support mechanisms have evolved to support new build renewables, the current framework isn’t suitable for pumped storage projects that can have a lifespan of many decades.

Drax’s plans would enable more homegrown renewable power to come online to strengthen the UK’s energy security and lower carbon emissions. This additional capacity could be available within eight years.

To secure private investment in these projects, get shovels in the ground and work underway, developers need to know the policy environment they will be operating in.

Abandoning or delaying net zero will not save the country money, it will increase our reliance on foreign gas, leaving households at the mercy of international markets which no UK government can control.

Find out more about Cruachan 2 here.

In Scotland alone there is more than 4.3 GW of storage projects in planning or awaiting construction – this is enough capacity to power around three million homes.

Drax, alongside the developers of some of these other projects, has put forward plans for policies which would create the certainty needed to incentivise investment and kick start work to build the storage capacity this country needs for energy security.

These include introducing a cap and floor regime – the same support mechanism which was instrumental in the successful roll-out of interconnectors in Britain.

I urge the new Conservative Party leader to make the government’s response to these proposals a priority, as part of the package of measures needed to bolster the UK’s long term energy security and to bring the longer-term cost of energy down.

With the right policies to unlock investment, the UK can lead the world in energy storage technologies which are urgently needed to keep the lights on, cut carbon emissions and keep us on track to reach net zero.

This article was first published by Business Green. 

Capacity Market Agreements

Cruachan pylons

Drax Group plc
(“Drax” or the “Group”; Symbol:DRX)
RNS Number : 8747R

T-4 auction – provisional results for existing pumped storage and hydro assets

Drax confirms that it has provisionally secured agreements to provide a total of 617MW of capacity (de-rated 582MW) principally from its pumped storage and hydro assets(1). The agreements are for the delivery period October 2024 to September 2025, at a price of £18/kW(2) and are worth around £10 million in that period. These are in addition to existing agreements which extend to September 2024.

T-4 auction – provisional results for new build system support assets

Drax confirms that it has provisionally secured 15-year agreements for three new 299MW (de-rated 284MW) Open Cycle Gas Turbine (OCGT) projects at sites in England and Wales(3). The agreements are for the delivery period October 2024 to September 2039, at a price of £18/kW(2) and are worth around £230 million in that period.

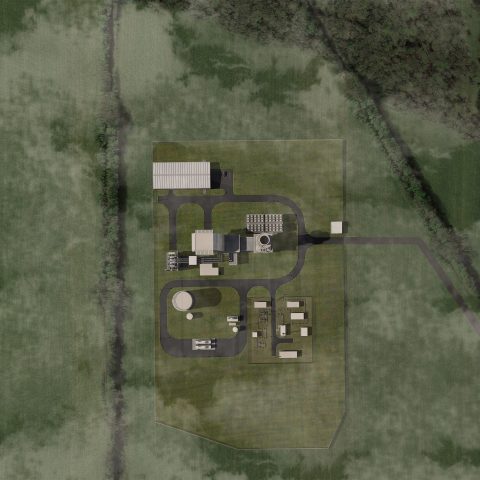
Artist’s impression of a Drax rapid-response gas power station (OCGT)

Artist’s impression of a rapid-response gas power station (OCGT)

These assets are intended to operate for short periods of time to meet specific system support needs. As the UK transitions towards a net zero economy, it will become increasingly dependent on wind generation and as such, fast response system support technologies such as these OCGTs are increasingly important to the energy system as a means to enable more wind to run more often and more securely.

The total capital cost of these projects is approximately £80-90 million each, with a build time of around two years.

A further OCGT project participated in the auction but exited above the clearing price and did not accept an agreement.

Drax will now evaluate options for all four OCGT projects including their potential sale.

Continued focus on biomass strategy and the development of negative emissions

In December 2019 Drax announced an ambition to become a carbon negative company by 2030 using Bioenergy Carbon Capture and Storage (BECCS) and the Group remains focused on its biomass strategy. In January 2021 Drax completed the sale of its Combined Cycle Gas Generation (CCGT) assets and in March 2021 ends commercial coal generation. Drax believes that its remaining portfolio of sustainable biomass, pumped storage and hydro will be amongst the lowest carbon generation portfolios in Europe.

Enquiries

Drax Investor Relations: Mark Strafford

+44 (0) 7730 763 949

Media

Drax External Communications: Ali Lewis

+44 (0) 7712 670 888

Website: www.drax.com/uk

Capacity Market agreements for existing assets

Engineer below Cruachan Power Station dam

RNS: 3530F
Drax Group plc

(“Drax” or the “Company”; Symbol:DRX)

Drax confirms that it has provisionally secured agreements to provide a total of 2,562MW of capacity (de-rated 2,333MW) from its existing gas, pumped storage and hydro assets(1). The agreements are for the delivery period October 2023 to September 2024, at a price of £15.97/kW(2) and are worth £37 million in that period. These are in addition to existing agreements which extend to September 2023.

Drax did not accept an agreement for the 60MW Combined Cycle Gas Turbine (CCGT) at Blackburn Mill.

A new-build CCGT at Damhead Creek and four new-build Open Cycle Gas Turbine projects participated in the auction but exited above the clearing price and did not accept agreements.

Enquiries:

Drax Investor Relations: Mark Strafford
+44 (0) 7730 763 949

Media:

Drax External Communications: Ali Lewis
+44 (0) 7712 670 888

Website: www.drax.com/uk

Notes:

  1. Existing assets – gas (Damhead Creek, Rye House, Shoreham and three existing small gas turbines at Drax Power Station), Cruachan Pumped Storage and the Galloway hydro scheme (Tongland, Kendoon and Glenlee).
  2. Capacity Market agreements stated in 2018/19 real-terms, with payments indexed to UK CPI.

END

Capacity Market agreements for existing assets and review of coal generation

Drax's Kendoon Power Station, Galloway Hydro Scheme, Scotland

RNS Number : 6536B

T-3 Auction Provisional Results

Drax confirms that it has provisionally secured agreements to provide a total of 2,562MW of capacity (de-rated 2,333MW) from its existing gas, pumped storage and hydro assets(1). The agreements are for the delivery period October 2022 to September 2023, at a price of £6.44/kW(2) and are worth £15 million in that period. These are in addition to existing agreements which extend to September 2022.

Drax did not accept agreements for its two coal units(3) at Drax Power Station or the small Combined Cycle Gas Turbine (CCGT) at Blackburn Mill(4) and will now assess options for these assets, alongside discussions with National Grid, Ofgem and the UK Government.

A new-build CCGT at Damhead Creek and four new-build Open Cycle Gas Turbine projects participated in the auction but exited above the clearing price and did not accept agreements.

T-4 Auction

Drax has prequalified its existing assets(5) and options for the development of new gas generation to participate in the T-4 auction, which takes place in March 2020. The auction covers the delivery period from October 2023.

CCGTs at Drax Power Station

Following confirmation that a Judicial Review will now proceed against the Government, regarding the decision to grant planning approval for new CCGTs at Drax Power Station, Drax does not intend to take a Capacity Market agreement in the forthcoming T-4 auction. This project will not participate in future Capacity Market auctions until the outcome of the Judicial Review is known.

Enquiries:

Drax Investor Relations
Mark Strafford
+44 (0) 7730 763 949

Media:

Drax External Communications
Matt Willey
+44 (0) 0771 137 6087

Photo caption: Drax’s Kendoon Power Station, Galloway Hydro Scheme, Scotland

Website: www.drax.com/uk

Result of General Meeting

RNS Number : 2803L
Drax Group PLC
No.Brief DescriptionVotes For%Votes Against%Votes TotalVotes Withheld
1. To approve the acquisition of the entire issued share capital of ScottishPower Generation Limited268,580,49485.7544,619,02714.25313,199,52121,841

The resolution was carried. Completion of the acquisition is expected to occur on 31 December 2018.

The number of shares in issue is 407,193,168 (of which 12,867,349 are held in treasury. Treasury shares don’t carry voting rights).

Votes withheld are not a vote in law and have not been counted in the calculation of the votes for and against the resolution, the total votes validly cast or the calculation of the proportion of issued share capital voted.

A copy of the resolution is available for inspection in the Circular, which was previously submitted to the UK Listing Authority’s Document Viewing Facility, via the National Storage Mechanism at www.morningstar.co.uk/uk/NSM.

The Circular and the voting results are also available on the Company’s website at www.drax.com/uk.

Enquiries

Drax Investor Relations

Mark Strafford
+44 (0) 1757 612 491
+44 (0) 7730 763 949

Media, Drax External Communications

Matt Willey
+44 (0) 7711 376 087

Website: www.drax.com/uk

END

Acquisition agreement amended to mitigate risk to 2019 capacity payments

RNS Number: 1455J
THIS ANNOUNCEMENT CONTAINS INSIDE INFORMATION

The revised contractual arrangements are designed to mitigate the risk to 2019 capacity payments arising from the recent suspension of the Capacity Market.

Commenting on today’s announcement Will Gardiner, Chief Executive Officer of Drax Group, said:

“The strategic merits of this acquisition remain unchanged and the Board believes there is a compelling logic in our move to add further flexible sources of power to our offering, which will accelerate our ability to deliver our strategic vision of a lower-carbon, lower-cost energy future for the UK.

“The capacity market is a central pillar of the UK’s energy policy and ensures security of supply while minimising costs to consumers. The Government has stated it is working closely with the European Commission to aid their investigation and to reinstate the full capacity market regime, including existing agreements, as soon as possible.

“To mitigate the risk that capacity payments take time to be restored, we have agreed revised terms which provide protection in 2019. Beyond 2019, while reinstatement of the Capacity Market is the most likely outcome, we considered other outcomes, the more plausible of which would still deliver returns in excess of Drax’s weighted average cost of capital.

“The acquisition makes financial and strategic sense, delivering material value to our shareholders through long-term earnings and attractive returns.”

Capacity Market

On 15 November 2018, the General Court of the European Union issued a ruling annulling the European Commission’s 2014 decision not to undertake a more detailed investigation of the UK Government’s scheme establishing the Capacity Market (the “Ruling”). The Ruling imposed a “standstill period” while the European Commission completes a further state aid investigation into the Capacity Market. Payments to generators scheduled under existing capacity agreements and the holding of future capacity auctions have been suspended.

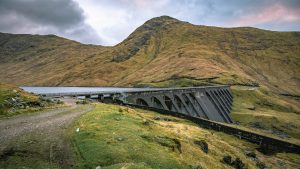
Cruachan Power Station on Loch Awe, Argylle and Bute

Contracted capacity payments make up a significant proportion of the earnings of the Portfolio. For the period from 1 January 2019 to 30 September 2022, the Cruachan pumped storage hydro asset has contracted capacity payments of £29 million, the Galloway run-of-river hydro assets have contracted capacity payments of £5m million, and the Combined Cycle Gas Turbine assets have contracted capacity payments of £122 million in aggregate.

Drax notes the UK Government’s statement in response to the Ruling that it is working closely with the European Commission to aid their investigation and to seek a timely state aid re-approval decision for the Capacity Market. The UK Government also confirmed that the Ruling does not change its belief that Capacity Market auctions are the most appropriate way to deliver secure electricity supplies at the lowest cost and that the Ruling was decided on procedural grounds and did not constitute a direct challenge to the design of the Capacity Market itself.

Based on the information available and legal advice it has received, Drax believes that the most likely outcome is that the European Commission will re-approve the existing Capacity Market in its current or a broadly similar form.

Despite the above, Drax recognises there is some uncertainty whether the contracted capacity payments for the 2018/19 Capacity Market year, which are currently suspended, will be paid by the UK Government. To mitigate the risk that these payments are not received for the 2018/19 Capacity Market year, Drax has agreed with Iberdrola certain amendments to the agreement signed on 16 October 2018.

Arrangements with Iberdrola in respect of 2018/19 capacity payments

Drax and Iberdrola have agreed a risk sharing mechanism in respect of capacity payments for the period 1 January 2019 to 30 September 2019, worth £36 million. If less than 100% of these payments are received and the gross profit of the Portfolio for the full year 2019 (the “2019 Gross Profit”) is lower than expected, Drax will receive a payment from Iberdrola of up to £26 million. The mechanism also gives Iberdrola the opportunity to earn an upside of up to £26 million if less than 100% of these payments are received but the Portfolio performs better than expected in 2019(1).

Under these arrangements, if less than 100% of these capacity payments are received:

  1. Iberdrola will make a payment to Drax if the 2019 Gross Profit is less than £155 million. The payment will be an amount equal to 72% of any shortfall in the 2019 Gross Profit below £155 million. The amount of the payment is capped at the lower of the amount in respect of capacity payments due to the Portfolio but not received and £26 million; and
  2. Drax will make a payment to Iberdrola if the 2019 Gross Profit is more than £165 million. The payment will be an amount equal to 72% of any amount by which the 2019 Gross Profit exceeds £165 million. The amount of the payment is capped at the lower of the amount in respect of capacity payments due to the Portfolio but not received by Drax and £26 million.

If subsequently Drax receives any capacity payments in respect of the period 1 January 2019 to 30 September 2019, Drax will pay 72% of those amounts to Iberdrola capped at the amount paid by Iberdrola to Drax under the mechanism above.

Drax and Iberdrola have agreed that capacity payments due to the Portfolio in respect of the period before completion will be passed through to Iberdrola.

Any payments pursuant to the arrangements with Iberdrola will be cash adjustments to the consideration and not included in EBITDA(2).

Benefits of the acquisition

Shoreham Power Station, West Sussex

Based on Drax’s expectations of the position that is most likely to be achieved in relation to the Capacity Market following the Ruling, Drax believes the Acquisition represents an attractive opportunity to create significant value for shareholders and is expected to deliver returns significantly in excess of Drax’s weighted average cost of capital.

Drax has considered other possible outcomes for the Capacity Market which are less likely but may ensue and if they did the financial effects of the Acquisition may be adversely affected.

Drax believes that if the more plausible of these outcomes were to ensue the returns from the Acquisition would still be in excess of the Drax’s weighted average cost of capital.

Drax has not attempted to quantify the effect if the less plausible of these other outcomes were to ensue – if there were no Capacity Market or similar mechanism or if significant structural changes were made to the Capacity Market. Drax sees these as a remote possibility and notes that in those circumstances it believes the loss or reduction of capacity payments could be mitigated by increases in wholesale power prices.

The Acquisition strengthens Drax’s ability to pay a growing and sustainable dividend. Drax remains committed to its capital allocation policy and to its current £50 million share buy-back programme, with £42 million of shares purchased to date.

2019 profit forecast

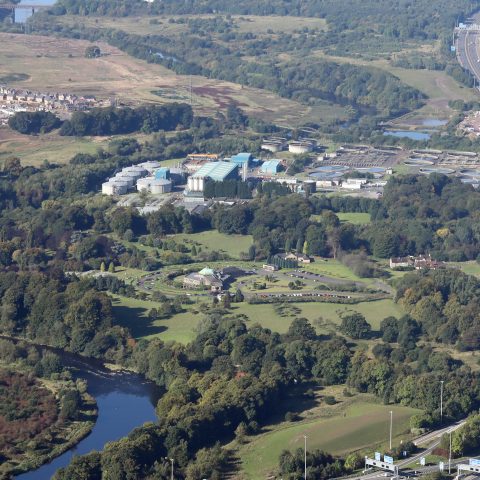
Daldowie Fuel Plant, Glasgow

Based on recent power and commodity prices and assuming that all contracted capacity payments are received, the Portfolio is expected to generate EBITDA in 2019 in a range of £90 million to £110 million, from gross profits of £155 million to £175 million, of which around two thirds is expected to come from non-commodity market sources, including system support services, capacity payments, ROCs(3) and the Daldowie energy-from-waste plant.

If, in light of the Ruling, the contracted capacity payments payable in 2019 in respect of the Portfolio are not received or accrued in 2019, the expected EBITDA for the Portfolio in 2019 would be reduced by up to £47 million (from a range of £90 million to £110 million) down to a range of £43 million to £63 million before considering mitigating factors. Drax believes that the arrangements agreed with Iberdrola mitigate in economic terms the majority of the risk that those suspended capacity payments will not be paid.

Assuming performance in line with current expectations and if all capacity payments due in 2019 are received before the end of 2019, net debt to EBITDA is expected to fall to Drax’s long-term target of around 2x by the end of 2019. If capacity payments are not received in 2019, net debt to EBITDA is expected to fall to around 2x during 2020.

Drax current trading and 2018 outlook

Following the Ruling, £7 million of contracted capacity payments relating to 2018, principally in relation to Drax’s remaining two coal-fired units, will not be paid as and when expected. Taking this into account, and following Drax’s recent good trading performance and assuming continued good operational availability for the remainder of the year, Drax’s full year EBITDA outlook remains in line with previous expectations, with net debt to EBITDA expected to be around 1.5x for the full year, excluding the impact of the Acquisition.

Process

On 1 November 2018, the Competition and Markets Authority informed Drax that it had no further questions in connection with the proposed Acquisition at that stage, which resulted in the competition condition under the Acquisition agreement being satisfied. Completion of the Acquisition is therefore currently expected to occur on 31 December 2018 assuming that the shareholder approval condition is satisfied by that date.

A combined shareholder circular and notice of general meeting containing the unanimous recommendation of the Board to approve the Acquisition will be posted as soon as practicable.

Other matters

Drax expects to announce its full year results for the year ending 31 December 2018 on 26 February 2019.

Notes

  1. Arrangements with Iberdrola in respect of 2018/19 capacity payments – only applicable if less than 100% of these capacity payments are received. Any payments pursuant to the arrangements with Iberdrola will be cash adjustments to the consideration and not included in EBITDA.Implied EBITDA is included in the table for reference only and is not a metric included in the mechanism, which is based on gross profit.
    The amount of the payment is capped at the lower of the amount in respect of capacity payments due to the Portfolio but not received by Drax and £26 million.
    2019 Gross Profit £mImplied EBITDA based on 2019 Gross Profit £mPayment made to / (by) Drax capped at £26m £m*
    119 or lower54 or lower26
    1296419
    1397412
    149844
    155900
    1651000
    175110-7
    185120-14
    195130-22
    201 or higher136 or higher-26

    *Payment made to / (by) Drax will be classified as a cash adjustment to the consideration rather than as gross profit.
  2. EBITDA means earnings before interest, tax, depreciation, amortisation, unrealised profits and losses on derivative contracts and material or one-off items that do not reflect the underlying trading performance of the business. 2019 EBITDA is stated before any allocation of Group overheads.
  3. Renewable Obligation Certificates.

Enquiries

Drax Investor Relations:

Mark Strafford
+44 (0) 1757 612 491
+44 (0) 7730 763 949

Media

Drax External Communications:

Matt Willey
+44 (0) 7711 376 087

Ali Lewis
+44 (0) 7712 670 888

J.P. Morgan Cazenove (Financial Adviser and Joint Corporate Broker)

+44 (0) 207 742 6000
Robert Constant
Jeanette Smits van Oyen
Carsten Woehrn

Royal Bank of Canada (Joint Corporate Broker):

+44 (0) 20 7653 4000
James Agnew
Jonathan Hardy