Tag: electric insights

Where is Britain’s electricity system heading? A conversation with Will Gardiner and Iain Staffell

Britain’s energy system is being pulled in many directions at once, with record levels of renewable generation alongside ongoing challenges around affordability, security and resilience.

As part of the Q2 2026 Electric Insights analysis, our CEO Will Gardiner spoke with Electric Insights author and Associate Professor of Sustainable Energy at Imperial College London, Iain Staffell, about what Britain’s latest electricity trends reveal about the direction of the power system and what it will take to deliver reliable, affordable net zero electricity.

Watch the full video conversation here:

Or read the transcript here:

Iain: Hello, I’m Iain Staffell, Associate Professor of Sustainable Energy at Imperial College London and author of Electric Insights. Today, I’m joined on the call by Will Gardiner, CEO of Drax, as part of our Electric Insights Quarterly analysis. We’ll look at what Britain’s latest electricity trends tell us about where the system is heading and what it will take to make net zero power more affordable and reliable.

Will, thank you for joining me. It feels like Britain’s energy system is being pulled in every direction at once. Bills remain stubbornly high, security is back at the top of the agenda, and we’ve struggled through record temperatures. But we also have record levels of renewable generation. When you put all of these trends together, what stands out the most?

Will: Hi, Iain, and thanks very much for having me today. And there’s definitely a feeling that we’ve made, we here in Britain have made real progress in decarbonising the power system. Now we have a real opportunity to turn some of the challenges into solutions in a way that will strengthen energy security, support growth and deliver wider benefits.

So for me, for example, the idea that actually people talk about Clean Power 2030. Are we going to get there by 2030? And for me, that’s not really the question. I mean, the question is we are going to get there and it’s not so important as to when it’s a question of will. And so I think for me, we need to continue this plan of rolling out homegrown renewables because they are doing much of the heavy lifting. We are reducing reliance on imported fuels. And as we know, in a world where imported fuels, often the price is impacted by geopolitics in ways that is very unhelpful for improving energy security while also reducing emissions and lowering bills. The key challenge we have, of course, is that we need to be fast and we need to be more joined up.

You know, we at Drax have real plans, for example, to add more generation. So we’re adding solar, we’re adding wind. We want to add batteries. And it’s just very difficult still to get stuff connected. So we need to be able to actually join things up and add more stuff that’s actually going to make this transition happen.

But what we’re doing at Drax, is we’re all about delivering resilient, reliable, renewable power and investing in the flexible, low carbon technologies that we need to effectively meet demand.

So we’re looking beyond single technologies. It’s a whole system challenge. How do we get a system which allows for dispatchable renewable, Sorry, for intermittent renewable generation, as in wind and solar, to be more supported by dispatchable generation, whether that’s biomass, whether that’s batteries, whether that’s long duration storage. So I think that’s the whole system challenge I think we need to sort of focus on solving.

But that’s my perspective Iain. And I’d be much more interested in what does the data say to you about where we’re heading and are we heading in the right direction?

Iain: Yeah, I’d say broadly, yes. When wind and solar now produced 40% of our electricity in Britain, cutting the need for imported gas. But the data also show the practical challenges that this is causing. I mean, we’ve got renewables being curtailed. We’ve got more hours with negative power prices and there’s growing strain on the balancing system. So the direction’s encouraging. But we’re paying the price for falling behind on flexibility.

And I think the cost of energy is what concerns most people. And critics point to rising offshore wind prices, expensive grid reinforcement and curtailment costs. And they ask whether the economics of the energy transition still stack up. And how do you respond to that?

Will: I fundamentally do believe that the economics of the transition stack up, right? I mean, things like wind, solar batteries, the technologies that are driving the advancements in those technologies are continuing to drive costs down. Well, at the same time, fossil fuels continue to be volatile. They continue to be impacted by geopolitics, as I already mentioned. So renewables reduces our exposure to that volatility. But obviously there’s also a cost. And that’s about again how do we find that balance.

We have to invest in the grid. We have to invest in storage. We have to invest in flexibility so we can actually to balance the supply and demand. And as I mentioned before, we need to invest in dispatchable low carbon generation that makes renewable power possible.

So one of the things that I think we in the again, in Britain should be more proud of and sort of speak more sort of proudly and happily about, is that we have had policy certainty. We’re very close to policy certainty for a long time about the generation of trying to move to a decarbonised energy system, and that’s really important. And that’s been, I think, more significant than in many countries. And as a result, we’ve made a lot of progress. And the next step is actually how do we now start to encourage more of that flexibility or that resilience that can support intermittent renewables.

Iain: So I mean, you talk about all of the sort of incredible achievements and the investment that we’ve had, but it’s going to take a staggering amount of coordinated work to meet the infrastructure needs over the next decade.

You know, the government’s Clean Power 2030 targets imply adding about 60 to 70GW of solar and wind capacity this decade. So that’s more than doubling what we currently have on the system. Do you think the main challenge is now the technology, or is it delivering it quickly enough and at the right price?

Will: So I actually think the technology is ready. And actually I’m not sure ready is the right phrase. The technology continues to evolve in a positive way. Batteries are going from 2 hours to 4 hours, ultimately to eight hours. The efficiency of solar panels continues to improve. So the technology is there, you know, and many developers like ourselves have significant pipelines, solar, battery storage, etc. that they want to put in place. So I think the technology is there, the investor base is there, and it’s now really all about delivery. And that delivery is the hard part and the barriers are familiar. So planning, getting grid connections, the supply chains, investor confidence. I mean investor confidence is still there. But we need to make sure we don’t lose that. So overcoming these things is not impossible. Absolutely I think we can do it. And I think we need, for example, finding ways to make it easier to get connections is a big topic for us here at Drax. So working on ways that we can do that. So for example, for me, one of the things that’s very challenging is that as a generator trying to get a connection, we don’t actually get firm commitment from the system operators. When this will happen, we could make those more firm and more legally binding. That would be a great step forward. So we need to find ways again to make it easier for us and others to deliver.

Iain: So you’re talking about generation and everyone focuses on electricity supply. It’s always a supply side issue. But do you think demand is also becoming a hot topic?

Will: Absolutely. I mean, and it’s really I would say maybe I’ll make three different points here. So people have been talking about for a while, maybe the last ten years, that electrification is the way to accelerate decarbonisation. And you’re starting to see that happen. That’s electric vehicles, electrifying heat, parts of industry. So that’s a trend that we’ve been seeing and I think starting to have an impact over time.

The second thing which we’re all aware of is data centres. And clearly they’re attracting a lot of controversy. But it is happening and it needs to happen, and we need to do it in the right way. That again will drive demand.

But the third part of this, which I think is an interesting question, is that if we could make the cost of electricity to the end user less expensive, then effectively, that would accelerate the drive and demand, and then the more demand you get a positive virtuous cycle, because if you can have more demand, you can spread the fixed cost of a lot of this grid reinforcement, for example, over a broader sort of land based that would bring the unit cost down over time. So ideas like, for example, moving some of the renewable cost off the energy or the electricity bill, moving on to general taxation, we think would be a very interesting idea to sort of drive the demand. So we think demand will grow, but we think there’s ways that government policy could accelerate that.

Iain: So I mean, a renewable power system has these problems of reduced asset utilisation, but it still has to always be there when people and businesses need electricity. And we all know that the wind doesn’t always blow and the sun doesn’t always shine. And I think batteries, they’re an excellent way for covering the short peaks. But Britain is a windy country, so unlike a lot of the other countries in the world, we need to keep power flowing for days or weeks at a time when it’s particularly cold and the weather is still. So to cope with our weather, we need to get serious about long duration energy storage and clean, dispatchable generation so that supply remains secure in all situations.

Will: Absolutely true. And long duration storage is absolutely part of our plans and we think the UK needs more of it. I think again, technology is helping move in that direction. For example, batteries get to be longer term. But as you say in the UK we left to complain about the weather, don’t we? But do you see that becoming more of a problem in the years ahead?

Iain: Yeah, absolutely. I mean, just look at the summer that we’ve been through. We’re seeing Britain’s climate changing before our eyes. You know, we’ve got heat waves and we’ve got droughts at a scale that we haven’t seen before. And I think climate resilience needs to become central to planning hotter summers, stronger winter storms and changing rainfall. They’re all affecting demand generation and the electricity infrastructure. I don’t think we can hold the design for the weather. I don’t think we can design for the weather that we remember from childhood. I mean, the power system needs to cope with wider swings and more extreme conditions that the future will throw at us.

But that said, I don’t want to finish on a negative. We’ve talked a lot about the challenges and the costs. So let me ask, what do you think are the biggest opportunities for Britain as we move forward with the Clean Power Plan?

Will: So, as we as we started this conversation, I think Britain has made more progress than many countries in decarbonising, which means we have a bigger share of power driven by intermittent renewables, means that we actually now are starting to adjust problems, like how do you build a grid to deal with that? And for companies like ours. How do you use technology to optimise when you dispatch it and how you deliver the power when it’s needed most, etc., from batteries or from peaking plants, those types of things and these types of challenges will become global challenges. Because, you know, my very strong view is that the world will move to a renewable system over time. And so the UK is developing skills that actually which could become exportable over time. We become very good at managing a dispatchable system which requires both intermittent renewables but also flexible generation, batteries, etc., to support it as we become the world’s leaders in that, that’s absolutely something that we should exploit. And so I think, again, building that system is something that should give the UK over time significant industrial advantage. And that’s what we’re working on here.

Iain: Well thank you very much Will. That’s great.

And if you want to find out more, head to Electric Insights for all the latest.
Britain’s solar boom needs energy storage to tackle evening price spikes, new report finds

Britain’s rapid growth in solar power is helping cut emissions from the electricity system, but a lack of storage is leaving the grid increasingly exposed to higher prices and periods of tight supply, according to the latest Drax Electric Insights quarterly report authored by independent academics from Imperial College London.

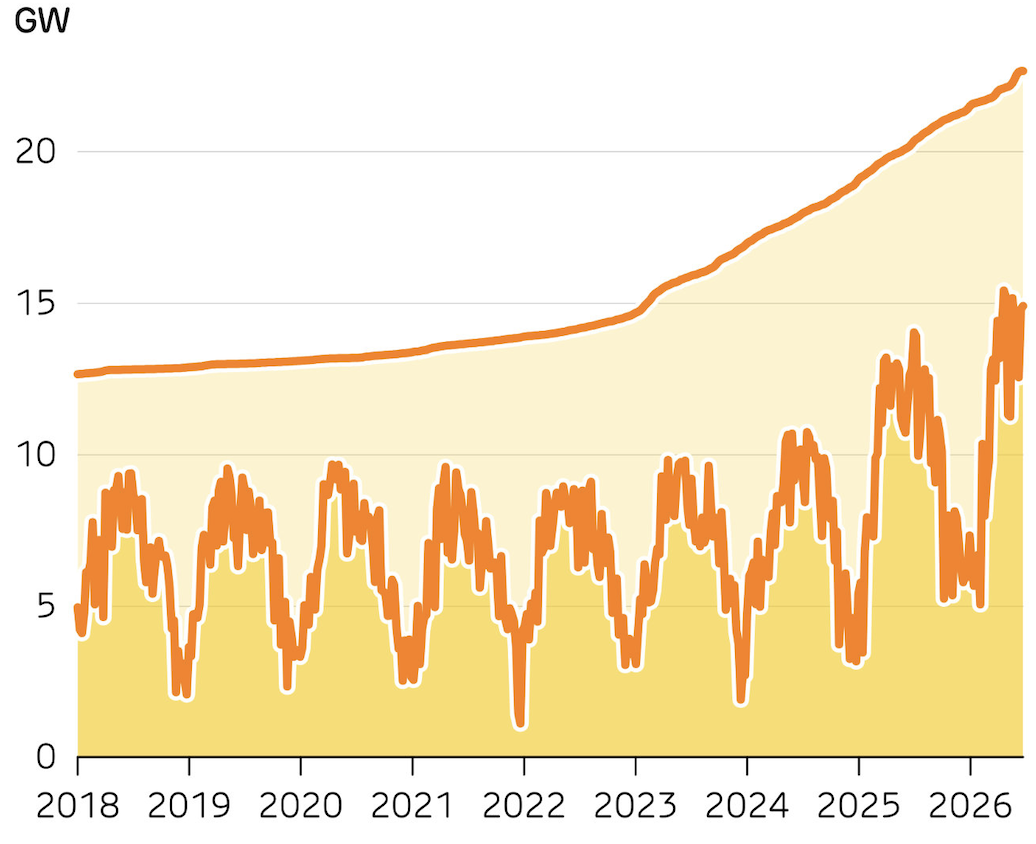
The report found that Britain’s power system can now operate with very high levels of low-carbon generation during periods of strong sunshine. Britain added 2 GW of solar capacity over the past year, and during April, solar generation reached a record 15.4 GW. This helped zero-carbon sources account for a record 98.8% of electricity supply for one half-hour period.

The installed capacity (top line) and peak power output (bottom line) of Britain’s solar panels. 

Strong solar generation reduces Britain’s reliance on gas during the day and helps meet demand for air conditioning during heat waves. The challenge comes later, as solar output falls sharply in the evening, just as electricity demand typically increases, leaving Britain reliant on gas-fired generation to fill the gap. In June, Britain’s wholesale electricity prices after 7pm rose to over double their level at 2pm.

June’s heatwaves exposed the pressures on the system. Wholesale electricity prices rose above £500/MWh, their highest ever recorded in the month of June, while NESO issued its first-ever summertime Electricity Margin Notice.

Heatwaves can put further pressure on the electricity system, as we have seen over the summer. Air conditioning and greater cooling load increases demand just as high temperatures reduce the efficiency of power lines and thermal plants. Calm, low-wind evenings can also add to the pressure, leaving grid operators with fewer sources of generation available to meet the required demand.

Dr Iain Staffell, lead author of the report and Associate Professor at Imperial College London, said:

“Britain’s solar success should not end when the sun goes down. Batteries, pumped hydro and other storage tech can keep that daytime electricity flowing into the evening, which will reduce our reliance on gas and exposure to foreign market price spikes.

“Every new solar panel strengthens the case for storage. We need to build the two together. Otherwise, we risk breaking clean-power records at lunchtime and paying for expensive gas-fired power by dinnertime.”

The Government’s Solar Roadmap aims to put solar panels on an extra 3 million homes, adding a further 10 GW by 2030. The report warns that this will need to be accompanied by investment in electricity storage, flexible infrastructure and other forms of reliable generation if the additional power is to be used effectively.

Will Gardiner, CEO, Drax said:

“There is a feeling that Britain has made real progress in decarbonising its power system and now has a real opportunity to turn some of its energy challenges into solutions that can strengthen energy security, support growth and deliver wider benefits. We need to continue the plan of rolling out homegrown renewables, because they are doing much of the heavy lifting, we are reducing reliance on imported fossil fuels, improving energy security, reducing emissions and lowering bills.

“The key challenge we have is we need to be faster and more joined up. At Drax we’re all about delivering resilient, reliable, renewable power today while investing in the flexible, low-carbon technologies that we need to effectively meet demand. This means looking beyond single technologies, it is a whole-system challenge, where renewable generation, dispatchable low-carbon power, storage and flexibility all need to work together.”

Read the full Electric Insights report here.

ENDS

Media contacts:

Kieran Wilson
E: [email protected]
T: 07729092807

About Drax

Drax’s purpose is to enable a zero carbon, lower cost energy future. Our strategic aims are to be a UK leader in flexible, renewable generation and a global leader in sustainable biomass pellet production.

Our operations

Drax owns and operates a portfolio of flexible, low-carbon and renewable UK power assets – biomass, hydro, pumped storage and OCGT generation – which provide dispatchable power and system support services to the electricity grid.

We are the UK’s largest source of renewable power by output, and Drax Power Station is the UK’s largest single source of renewable electricity by output.

Through our pellet production facilities in North America, Drax is a leading integrated producer of sustainable biomass.

Drax supplies renewable electricity to UK industrial and commercial customers, offering a range of energy-related services including energy optimisation, as well as electric vehicle strategy and management.

Global competition for battery storage

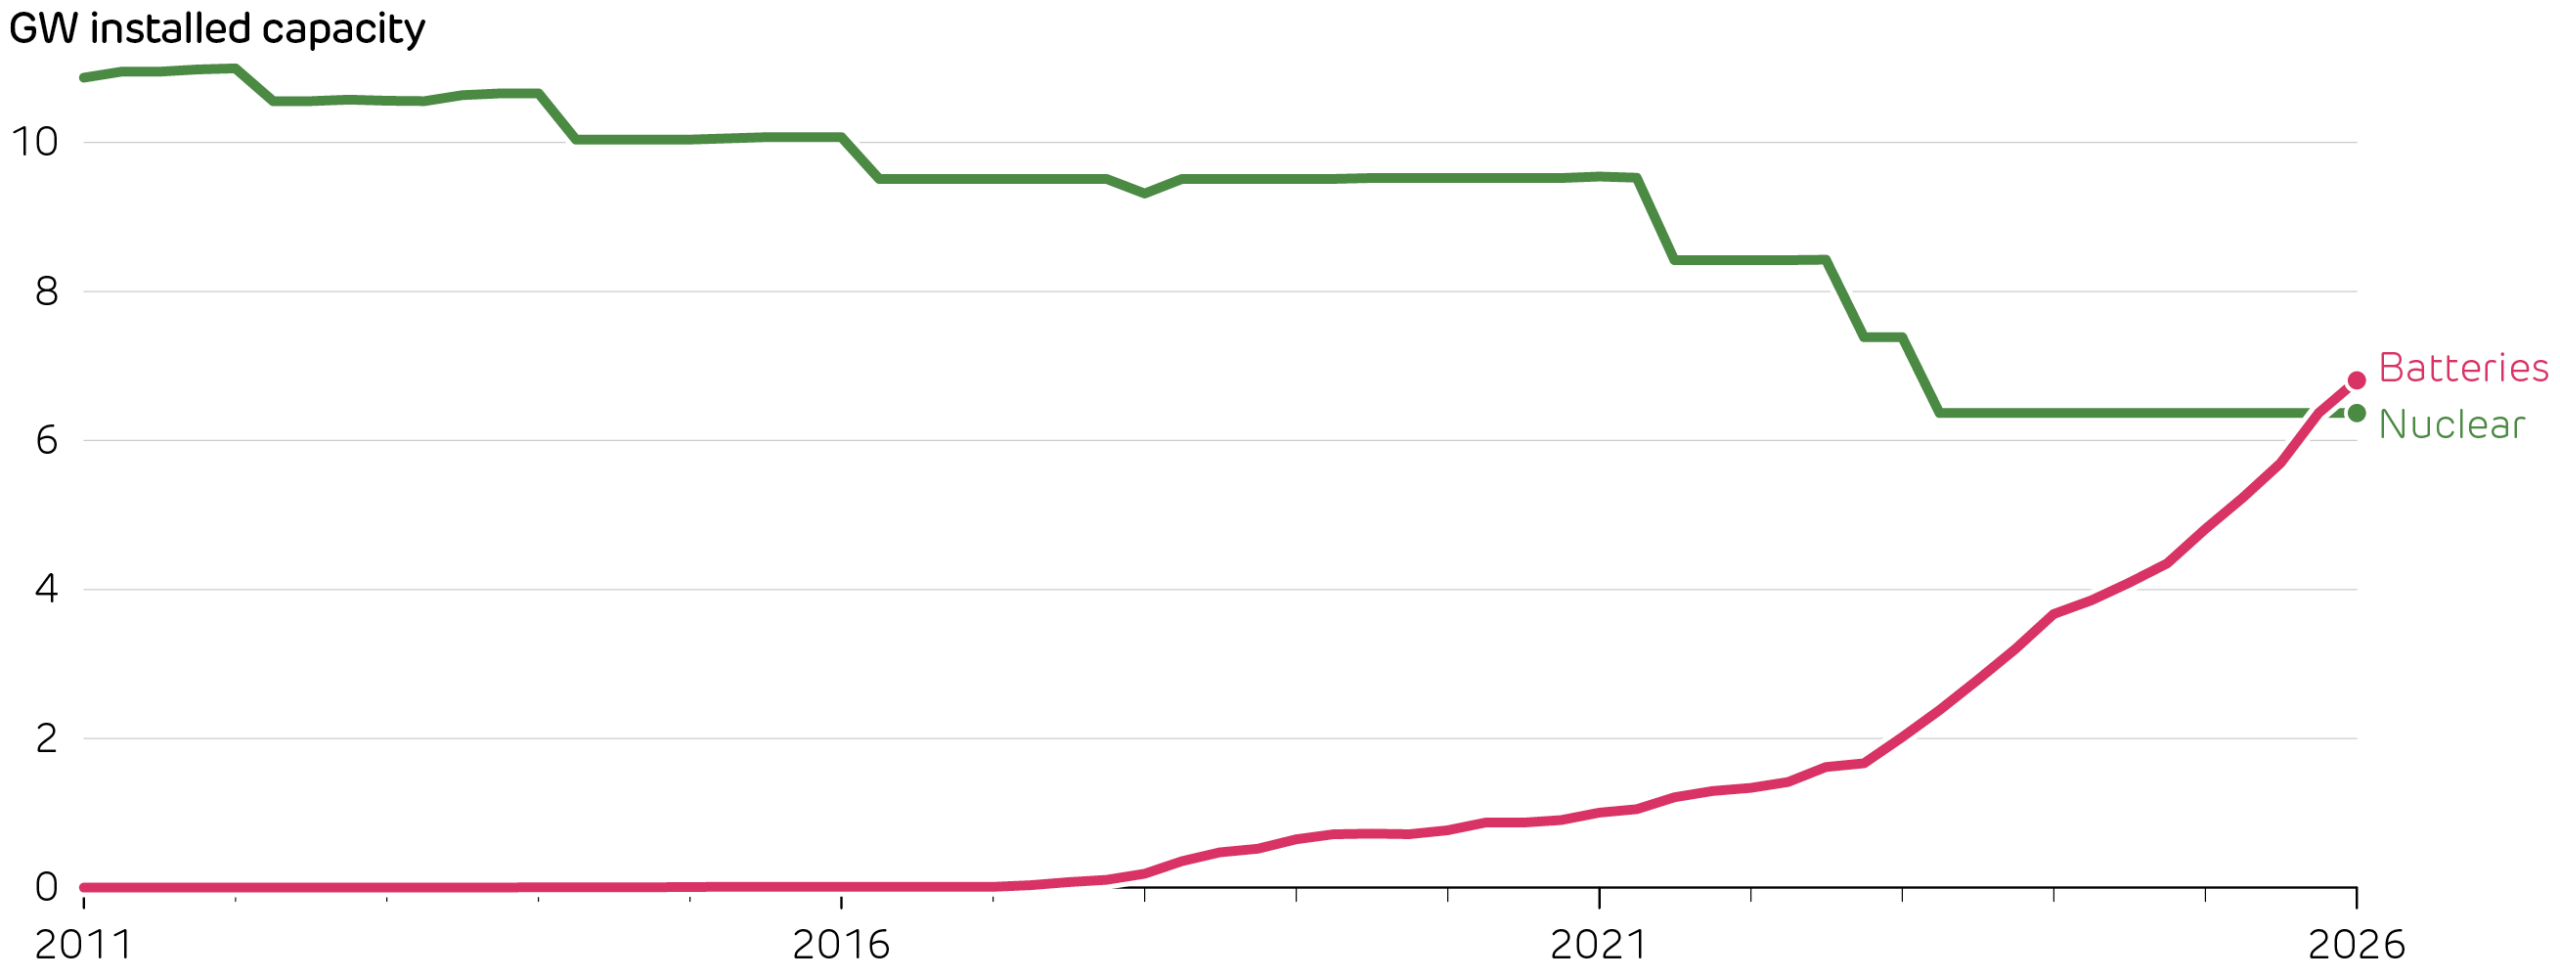
Britain is building batteries faster than any other part of its power system. Installed capacity has tripled in just three years. Batteries can now discharge more power than the entire nuclear fleet, a sign of how quickly the grid is changing. Since construction of Hinkley Point C began, Britain has installed nearly 7 GW of batteries. Hinkley Point’s 3.2 GW of reactors will not come online until at least 2030 (five years late), whereas new battery projects can be built in a matter of months.

Britain’s battery capacity has risen from 10 MW to nearly 7 GW, overtaking the headline capacity of the entire nuclear fleet in under a decade. The two technologies are not directly comparable, as batteries can only discharge for 1–4 hours before recharging, whereas nuclear reactors provide steady output around the clock.

Britain’s battery boom is impressive, but it must compete in a global race for investment. Storage is growing faster overseas as countries seek flexibility to absorb more wind and solar. Investors follow price signals, and battery revenues shift quickly with market regulations and price spreads. Battery revenues vary by one-quarter from year to year, so today’s hottest market can soon become crowded and less attractive.

Turkey shows how quickly the race can shift. It now has Europe’s largest pipeline of battery projects, beating Germany and Italy combined. This surge reflects a fast-growing power system turning to wind and solar to cut imports. Since 2022, new wind and solar projects have had to add battery capacity equal to their generation capacity.

Britain is taking the opposite approach: rather than mandating battery construction, the market decides how much to build. Tighter co-location or balancing requirements could make wind and solar more compatible with system operations, but could risk stalling investment. The Government is leaning towards market signals, with the Clean Flexibility Roadmap aiming to remove barriers and improve price signals for storage.

Energy storage helps Britain use more of the electricity it generates. Batteries respond to short-term swings in supply and demand within seconds, while pumped hydro provides large reservoirs to deliver electricity during longer periods of system stress. Together, they store surplus wind and solar to cut curtailment, and release it when demand peaks to smooth out prices.

To support the Clean Power targets, Britain must more than triple its current storage capacity by 2030. After building 5 GW of batteries in the last five years, Britain now has five years to build the next 20 GW. This will rely on investors remaining convinced this is Europe’s best place to build.

Read the full Q1 2026 Electric Insights report here.

Wind droughts show the need for low-carbon flexible generation

By Dr Iain Staffell, Imperial College London 

As our energy mix changes and a different weather challenge has been taking up the headlines, latest analysis from Electric Insights has revealed that the need for reliable low-carbon generation when the wind doesn’t blow and the sun doesn’t shine is becoming more important. Dr Iain Staffell took a look at the data.   

“Dunkelflaute” must surely be an early contender for the 2025 Oxford Dictionary word of the year.  A German word meaning “dark doldrums”, it is used in the energy world to describe a dark, cold, calm spell of weather during which very little energy can be generated with wind or solar power.

In December and January, Britain has faced two spells of so-called Dunkelflaute.  The first, hitting around the 12 December, saw wind – the largest source of energy in the UK last year overall – drop to 6% of total supply.  In response, gas power stations ramped up to their highest output ever recorded, supplying more than 73% of Britain’s electricity and sending power prices soaring.  Wind output dropped suddenly again in the New Year causing prices to hit £2,900/MWh (40 times their average) on 8 January.

This winter has again demonstrated some of the challenges we must address in reaching a clean power system by 2030.  The combination of a long cold snap and low wind speeds left Britain’s power system relying heavily on natural gas and imports, drawing down the nation’s gas storage to ‘concerningly low’ levels, and coming close to generation falling short of peak demand.  Options for low-carbon flexibility are urgently needed – both investing in new technologies and maintaining existing sources – as electricity supply and demand become more dependent on the weather.

Daily average electricity mix in Britain during mid-December, highlighting the Dunkelflaute period, and the difference between output from dispatchable technologies which we control, and those that are driven by the weather or foreign power markets.

Gas was not the only technology to help during the shortfall.  Biomass and hydro plants increased their output by 40% and 60% on the peak day (12 December) compared to the weekends before and after.  While this helped meet the shortfall of wind, the impact was muted as Britain has relatively little capacity of either technology.  In previous years, coal power stations would have also helped to meet demand, but the last one closed in September.  Pumped hydro and batteries helped meet the evening peak on the 12th, but these only supply power for a few hours, and so cannot help with multi-day shortages.

Interconnection with neighbouring countries also provides flexibility, but on the 12th when we most needed them, imports from abroad fell by half relative to the surrounding days.  Britain’s neighbours were suffering from the same wind drought, as weather systems are often the size of continents.  More power could have flowed into Britain, but only if our prices rose high enough.  This exposes a key problem with relying on interconnection to solve capacity shortages, which leaves countries competing for limited supply of power at the same time.

Altogether, this leaves gas as the only large-scale source of flexibility in the country.  This is a risky proposition on three fronts: affordability, energy security, and our climate goals.

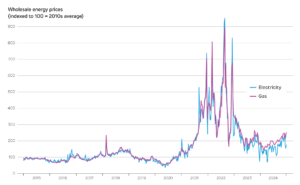
The cost of our gas dependence: We are still reeling from the gas price crisis.  Gas is very much the ‘crutch’ of the grid, and British electricity is more strongly swayed by gas prices than in any other European country, as we have so few alternatives for flexible generation (no coal, limited hydro and biomass, and less storage than neighbouring countries).  Gas sets the electricity price in 98% of hours, despite meeting only a third of electricity demand. That means Britain’s electricity prices track almost perfectly with gas prices, leaving consumers particularly vulnerable to price shocks, as seen during the recent gas price crisis.

The change in electricity and natural gas prices on Britain’s wholesale markets over the last decade, indexed to the 2010–19 average.  Gas prices increased by over 50% between February and December last year, dragging electricity prices up with them.

Energy security at risk: Relying so heavily on a single technology in times of system stress is leaving all our eggs in one basket.  Capacity was tight on 12 December and 8 January, causing NESO to issue rare Capacity Market Notices, a ‘blackout prevention system’ used to encourage generators to prepare extra capacity just in case.   Britain’s last coal plant has retired, all bar one nuclear plant is coming towards their end of life, and it is unclear if biomass will continue operating beyond 2027.  This all comes just as peak electricity demand is expected to grow from electric vehicles, heat pumps, AI, and data centres.  Unless more capacity is built or existing capacity has its lifetime extended, Capacity Market Notices will be increasingly likely in future.

The carbon challenge: Gas is the most polluting fuel remaining on the grid.  In just five years, government aim to run a clean power system, meaning just 5% of electricity produced from fossil fuels, down from over 25% today.  These plans include retaining almost all the current gas capacity to cover rare but intense periods of low renewable output.  Put together, this means gas plants will see fewer operating hours in the future, just as coal plants did over the last decade.  Either they will need to charge more for their output to cover costs, or the system needs to move more towards paying for availability than for output (e.g. capacity payments).

Phasing out gas will largely be achieved by scaling up wind and solar power, but that further intensifies the challenges posed by weather variability.  Both the CCC and NESO recognise that a balanced approach is needed, using all the tools at our disposal – flexible low-carbon generation, long-duration energy storage, interconnectors and a continued (but increasingly limited) role for gas.  Looking ahead, policy frameworks envisage the arrival of more low-carbon dispatchable power from 2030 onward.  This includes power stations equipped with carbon capture and storage (CCS), hydrogen, and long-duration storage.  All of these play little or no role in today’s power system, so the task now is to define a clear strategy for scaling and deploying these resources at pace, while avoiding cost escalation to consumers due to all the new investments.  By planning for Britain’s future energy needs and taking strategic action now, government, industry and investors can break free from paying for volatile gas expensive imports, and seize the opportunity of clean, stable, and lower cost electricity.

Read the full article here or in the Q4 2024 Electric Insights report, coming soon.

This article was written by Dr Iain Staffell, Senior Lecturer at Imperial College London, as part of the Electric Insights project. Drax does not guarantee the accuracy, reliability or completeness of this content.